NCEA Level 2 Accounting 91176 Prepare free practice questions with answers
Read the opening questions and their worked answers from paper 1 of our 20-paper NCEA Level 2 Accounting 91176 Prepare set, then download the 3-page PDF. These are original practice questions, not official past papers. Page updated 3 November 2026.

Topics: Adjustments in the general journal and general ledger (91176).
- Every adjustment is a journal entry with equal debits and credits: identify the two accounts, work out the amount (watch GST and rates), then debit the right one.
- A ledger account is finished by balancing after every entry and ending at 0 with a closing entry; the adjustment account (Prepayments, Accrued expenses or Revenue received in advance) is the contra entry.
Read the text of this sample
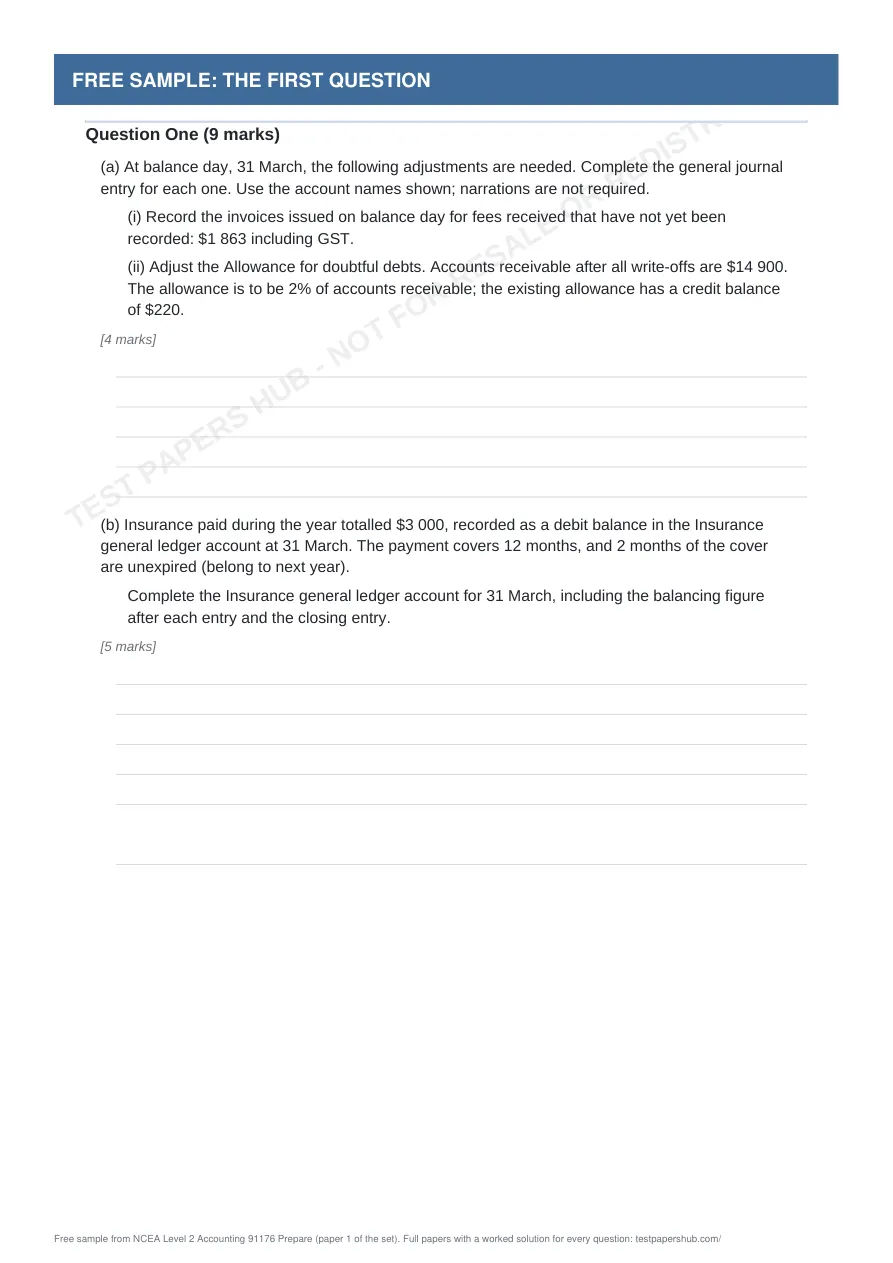
Question One (9 marks)
(a) At balance day, 31 March, the following adjustments are needed. Complete the general journal entry for each one. Use the account names shown; narrations are not required.
(i) Record the invoices issued on balance day for fees received that have not yet been recorded: $1 863 including GST.
(ii) Adjust the Allowance for doubtful debts. Accounts receivable after all write-offs are $14 900. The allowance is to be 2% of accounts receivable; the existing allowance has a credit balance of $220.
[4 marks]
(b) Insurance paid during the year totalled $3 000, recorded as a debit balance in the Insurance general ledger account at 31 March. The payment covers 12 months, and 2 months of the cover are unexpired (belong to next year). Complete the Insurance general ledger account for 31 March, including the balancing figure after each entry and the closing entry.
[5 marks]
Question 1 (9 marks) [Adjustments in the general journal and general ledger]
(a) At balance day, 31 March, the following adjustments are needed. Complete the general journal entry for each one. Use the account names shown; narrations are not required. (i) Record the invoices issued on balance day for fees received that have not yet been recorded: $1 863 including GST. (ii) Adjust the Allowance for doubtful debts. Accounts receivable after all write-offs are $14 900. The allowance is to be 2% of accounts receivable; the existing allowance has a credit balance of $220.
(a) Answer: (i) Dr Accounts receivable $1 863; Cr Fees received $1 620; Cr GST (payable) $243. (ii) Dr Doubtful debts $78; Cr Allowance for doubtful debts $78.
• Evidence level: Excellence (records each adjustment with equal debits and credits and a correctly calculated figure).
• Entry (i): The fees are earned this year, so they are revenue now (invoice basis): debit Accounts receivable for the full amount, credit Fees received $1 620 and GST (payable) $243. Entry: Dr Accounts receivable $1 863; Cr Fees received $1 620; Cr GST (payable) $243.
• Entry (ii): Required allowance = $14 900 × 2% = $298. This is $78 more than the existing $220, so increase the allowance: debit Doubtful debts, credit Allowance for doubtful debts $78. Entry: Dr Doubtful debts $78; Cr Allowance for doubtful debts $78.
• Check: in each entry total debits equal total credits.
(b) Insurance paid during the year totalled $3 000, recorded as a debit balance in the Insurance general ledger account at 31 March. The payment covers 12 months, and 2 months of the cover are unexpired (belong to next year). Complete the Insurance general ledger account for 31 March, including the balancing figure after each entry and the closing entry.
(b) Answer: Insurance: Prepayments $500 cr (balance $2 500 dr); Income summary $2 500 cr (balance 0)
• Evidence level: Merit (calculates the prepayment, balances the account and closes it).
• Prepayment = $3 000 × 2/12 = $500 (the unexpired part is an asset).
• Insurance account: 31/03 Balance $3 000 dr. Prepayments cr $500, balance $2 500 dr. Income summary (closing entry) cr $2 500, balance 0.
• Expense for the year = $3 000 − $500 = $2 500. Debit the Prepayments account for $500.
Your sample is downloading. Liked it? NCEA Level 2 Accounting 91176 Prepare Paper 1 is the full paper: three questions made of several multi-part problems answered in writing (constructed response, no multiple choice), with a worked solution for every part that shows whether it is aimed at Achieved, Merit or Excellence, with a worked solution for every question.
Get Paper 1 for A$11.99See all 20 papers from A$11.99More free NCEA (New Zealand) samples
Questions about this sample
What is in the NCEA Level 2 Accounting 91176 Prepare free sample?
The first 3 questions from paper 1 of the set, in the real exam layout, followed by the step-by-step worked answers. It is a 3-page PDF; this page shows the opening pages.
How many full NCEA Level 2 Accounting 91176 Prepare papers are there?
20 original papers for New Zealand Level 2 students preparing for NCEA external standard 91176. Each is three questions made of several multi-part problems answered in writing (constructed response, no multiple choice), with a worked solution for every part that shows whether it is aimed at Achieved, Merit or Excellence, with a worked solution for every question. Papers start at A$11.99 and download instantly as a PDF.
Are these official past papers?
No. The sample is taken from our own original practice paper and is not an official past paper or affiliated with any exam authority.