NCEA Level 3 Accounting 91404 Concepts free practice questions with answers
Read the opening questions and their worked answers from paper 1 of our 20-paper NCEA Level 3 Accounting 91404 Concepts set, then download the 4-page PDF. These are original practice questions, not official past papers. Page updated 3 November 2026.

Topics: Features of reporting entities and statutory requirements (91404).
- Limited liability limits a shareholder’s loss to the amount paid (or unpaid) on the shares; it does not protect the value of the investment.
- An audit does not guarantee the future; it gives users independent assurance that the information they use to decide is reliable.
Read the text of this sample
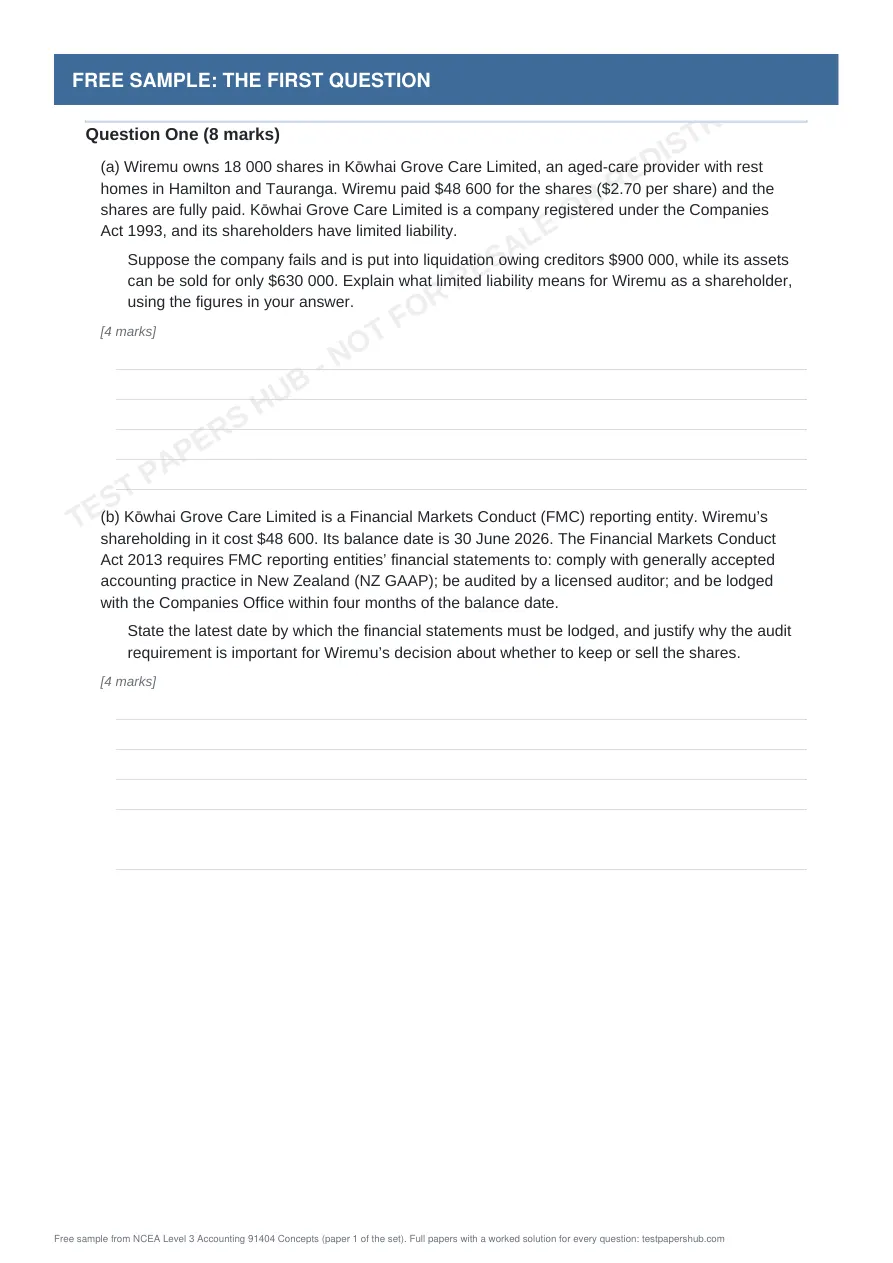
Question One (8 marks)
(a) Wiremu owns 18 000 shares in Kōwhai Grove Care Limited, an aged-care provider with rest homes in Hamilton and Tauranga. Wiremu paid $48 600 for the shares ($2.70 per share) and the shares are fully paid. Kōwhai Grove Care Limited is a company registered under the Companies Act 1993, and its shareholders have limited liability. Suppose the company fails and is put into liquidation owing creditors $900 000, while its assets can be sold for only $630 000. Explain what limited liability means for Wiremu as a shareholder, using the figures in your answer.
[4 marks]
(b) Kōwhai Grove Care Limited is a Financial Markets Conduct (FMC) reporting entity. Wiremu’s shareholding in it cost $48 600. Its balance date is 30 June 2026. The Financial Markets Conduct Act 2013 requires FMC reporting entities’ financial statements to: comply with generally accepted accounting practice in New Zealand (NZ GAAP); be audited by a licensed auditor; and be lodged with the Companies Office within four months of the balance date. State the latest date by which the financial statements must be lodged, and justify why the audit requirement is important for Wiremu’s decision about whether to keep or sell the shares.
[4 marks]
Question 1 (8 marks) [Features of reporting entities and statutory requirements]
(a) Wiremu owns 18 000 shares in Kōwhai Grove Care Limited, an aged-care provider with rest homes in Hamilton and Tauranga. Wiremu paid $48 600 for the shares ($2.70 per share) and the shares are fully
paid. Kōwhai Grove Care Limited is a company registered under the Companies Act 1993, and its shareholders have limited liability. Suppose the company fails and is put into liquidation owing creditors $900 000, while its assets can be sold for only $630 000. Explain what limited liability means for Wiremu as a shareholder, using the figures in your answer.
(a) Answer: Maximum loss $48 600; shortfall $270 000 not payable by Wiremu
• Evidence level: Merit (applies limited liability to the figures).
• Maximum loss for Wiremu = amount paid for the shares = 18 000 × $2.70 = $48 600.
• Shortfall to creditors = $900 000 − $630 000 = $270 000; Wiremu is not liable for it.
• Achievement: Limited liability means Wiremu cannot be required to pay the company’s debts out of personal assets; the company, not the shareholder, owes the creditors.
• Merit: Limited liability means Wiremu cannot be required to pay the company’s debts out of personal assets; the company, not the shareholder, owes the creditors. The most Wiremu can lose is the $48 600 paid for the shares, because the shares are fully paid and there is no further call on Wiremu.
• Excellence: Limited liability means Wiremu cannot be required to pay the company’s debts out of personal assets; the company, not the shareholder, owes the creditors. The most Wiremu can lose is the $48 600 paid for the shares, because the shares are fully paid and there is no further call on Wiremu. The shortfall of $270 000 ($900 000 − $630 000) is borne by the creditors, not by Wiremu; this is different from a sole trader, who would be personally liable for the whole shortfall. This protection is why people are willing to invest in a company such as Kōwhai Grove Care Limited.
(b) Kōwhai Grove Care Limited is a Financial Markets Conduct (FMC) reporting entity. Wiremu’s shareholding in it cost $48 600. Its balance date is 30 June 2026. The Financial Markets Conduct Act 2013 requires FMC reporting entities’ financial statements to: comply with generally accepted accounting practice in New Zealand (NZ GAAP); be audited by a licensed auditor; and be lodged with the Companies Office within four months of the balance date. State the latest date by which the financial statements must be lodged, and justify why the audit requirement is important for Wiremu’s decision about whether to keep or sell the shares.
(b) Answer: Lodge by 31 October 2026
• Evidence level: Excellence (gives the deadline and justifies the audit for the decision).
• Four months after 30 June 2026 is 31 October 2026.
• Achievement: The financial statements must be lodged by 31 October 2026 (four months after the balance date of 30 June 2026).
• Merit: The financial statements must be lodged by 31 October 2026 (four months after the balance date of 30 June 2026). An audit means an independent licensed auditor has checked that the statements comply with NZ GAAP.
Your sample is downloading. Liked it? NCEA Level 3 Accounting 91404 Concepts Paper 1 is the full paper: three written questions on accounting concepts for a New Zealand reporting entity: limited liability, NZ GAAP, accounting policies, element definitions and qualitative characteristics, with worked solutions showing Achieved, Merit and Excellence answers, with a worked solution for every question.
Get Paper 1 for A$11.99See all 20 papers from A$11.99More free NCEA (New Zealand) samples
Questions about this sample
What is in the NCEA Level 3 Accounting 91404 Concepts free sample?
The first 3 questions from paper 1 of the set, in the real exam layout, followed by the step-by-step worked answers. It is a 4-page PDF; this page shows the opening pages.
How many full NCEA Level 3 Accounting 91404 Concepts papers are there?
20 original papers for New Zealand Level 3 students preparing for NCEA external standard 91404. Each is three written questions on accounting concepts for a New Zealand reporting entity: limited liability, NZ GAAP, accounting policies, element definitions and qualitative characteristics, with worked solutions showing Achieved, Merit and Excellence answers, with a worked solution for every question. Papers start at A$11.99 and download instantly as a PDF.
Are these official past papers?
No. The sample is taken from our own original practice paper and is not an official past paper or affiliated with any exam authority.