NCEA Scholarship Accounting free practice questions with answers
Read the opening questions and their worked answers from paper 1 of our 20-paper NCEA Scholarship Accounting set, then download the 5-page PDF. These are original practice questions, not official past papers. Page updated 3 November 2026.
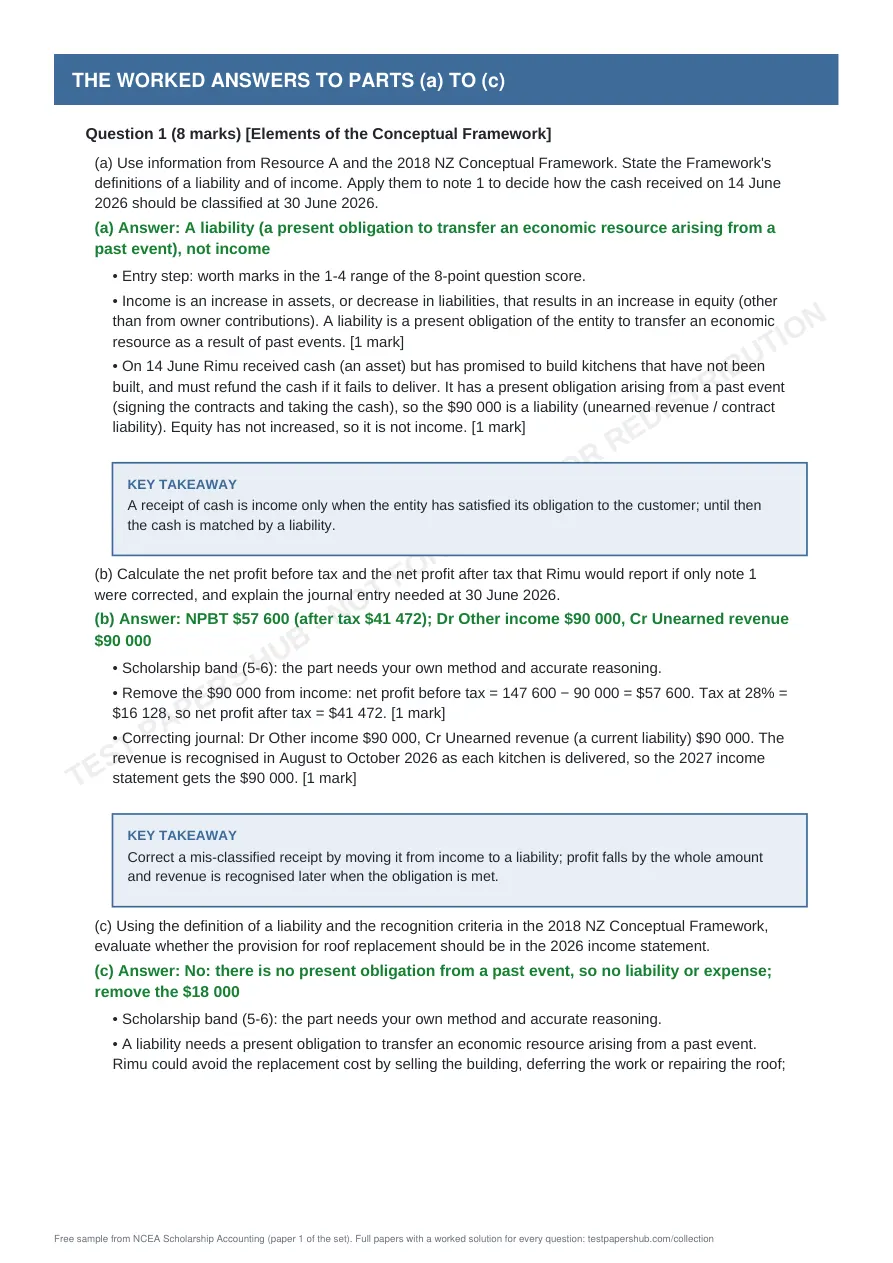
- A receipt of cash is income only when the entity has satisfied its obligation to the customer; until then the cash is matched by a liability.
- Correct a mis-classified receipt by moving it from income to a liability; profit falls by the whole amount and revenue is recognised later when the obligation is met.
- A future cost is a liability only if there is already an obligation to a third party; intending or expecting to spend money later is not a present obligation.
Read the text of this sample
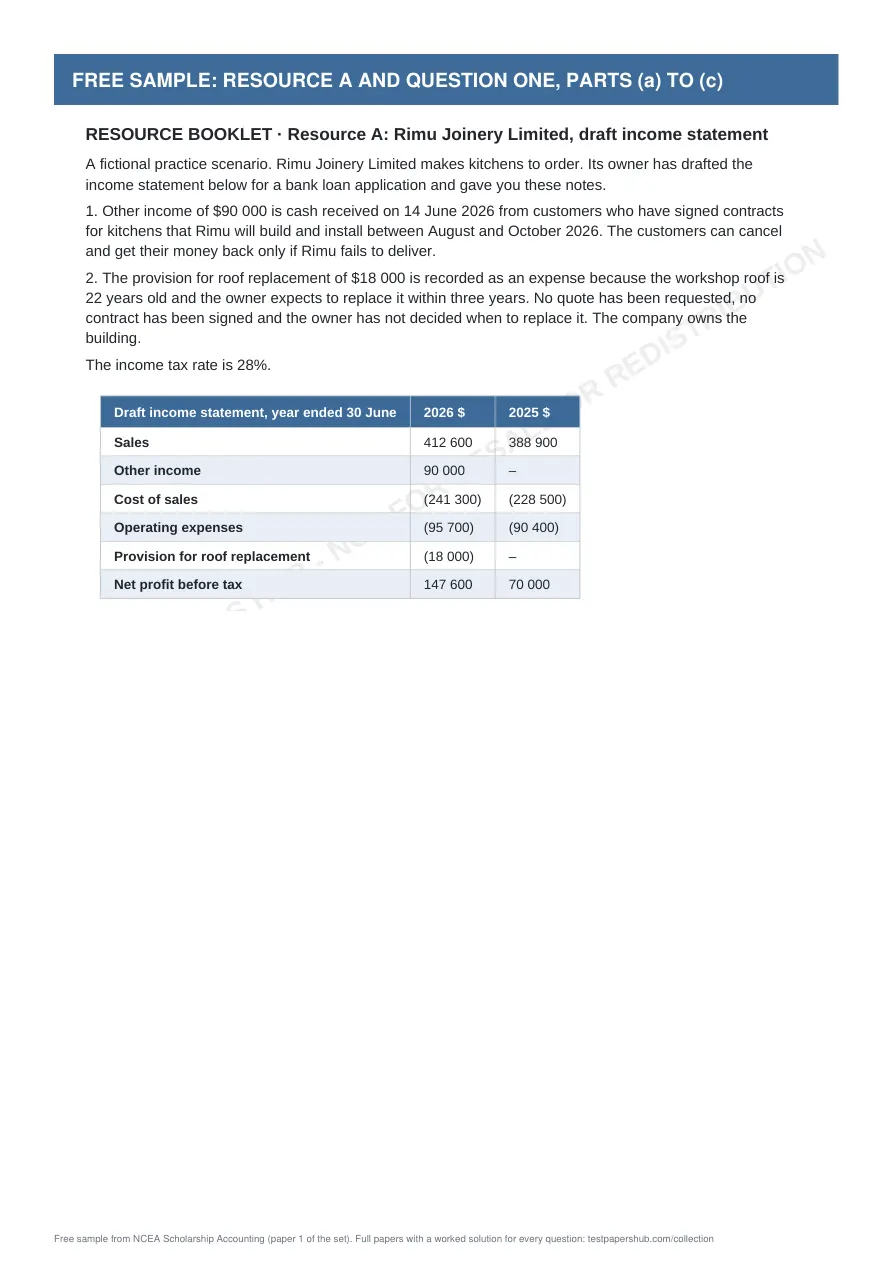
RESOURCE BOOKLET · Resource A: Rimu Joinery Limited, draft income statement
A fictional practice scenario. Rimu Joinery Limited makes kitchens to order. Its owner has drafted the income statement below for a bank loan application and gave you these notes.
1. Other income of $90 000 is cash received on 14 June 2026 from customers who have signed contracts for kitchens that Rimu will build and install between August and October 2026. The customers can cancel and get their money back only if Rimu fails to deliver.
2. The provision for roof replacement of $18 000 is recorded as an expense because the workshop roof is 22 years old and the owner expects to replace it within three years. No quote has been requested, no contract has been signed and the owner has not decided when to replace it. The company owns the building. The income tax rate is 28%. Draft income statement, year ended 30 June 2026 $ 2025 $ Sales 412 600 388 900 Other income 90 000 – Cost of sales (241 300) (228 500) Operating expenses (95 700) (90 400) Provision for roof replacement (18 000) – Net profit before tax 147 600 70 000 Question One (8 marks)
(a) Use information from Resource A and the 2018 NZ Conceptual Framework. State the Framework's definitions of a liability and of income. Apply them to note 1 to decide how the cash received on 14 June 2026 should be classified at 30 June 2026.
[2 marks]
(b) Calculate the net profit before tax and the net profit after tax that Rimu would report if only note 1 were corrected, and explain the journal entry needed at 30 June 2026.
[2 marks]
(c) Using the definition of a liability and the recognition criteria in the 2018 NZ Conceptual Framework, evaluate whether the provision for roof replacement should be in the 2026 income statement.
[2 marks]
Question 1 (8 marks) [Elements of the Conceptual Framework]
(a) Use information from Resource A and the 2018 NZ Conceptual Framework. State the Framework's definitions of a liability and of income. Apply them to note 1 to decide how the cash received on 14 June 2026 should be classified at 30 June 2026.
(a) Answer: A liability (a present obligation to transfer an economic resource arising from a past event), not income
• Entry step: worth marks in the 1-4 range of the 8-point question score.
• Income is an increase in assets, or decrease in liabilities, that results in an increase in equity (other than from owner contributions). A liability is a present obligation of the entity to transfer an economic resource as a result of past events. [1 mark]
• On 14 June Rimu received cash (an asset) but has promised to build kitchens that have not been built, and must refund the cash if it fails to deliver. It has a present obligation arising from a past event (signing the contracts and taking the cash), so the $90 000 is a liability (unearned revenue / contract liability). Equity has not increased, so it is not income. [1 mark]
(b) Calculate the net profit before tax and the net profit after tax that Rimu would report if only note 1 were corrected, and explain the journal entry needed at 30 June 2026.
(b) Answer: NPBT $57 600 (after tax $41 472); Dr Other income $90 000, Cr Unearned revenue $90 000
• Scholarship band (5-6): the part needs your own method and accurate reasoning.
• Remove the $90 000 from income: net profit before tax = 147 600 − 90 000 = $57 600. Tax at 28% = $16 128, so net profit after tax = $41 472. [1 mark]
• Correcting journal: Dr Other income $90 000, Cr Unearned revenue (a current liability) $90 000. The revenue is recognised in August to October 2026 as each kitchen is delivered, so the 2027 income statement gets the $90 000. [1 mark]
(c) Using the definition of a liability and the recognition criteria in the 2018 NZ Conceptual Framework, evaluate whether the provision for roof replacement should be in the 2026 income statement.
(c) Answer: No: there is no present obligation from a past event, so no liability or expense; remove the $18 000
• Scholarship band (5-6): the part needs your own method and accurate reasoning.
• A liability needs a present obligation to transfer an economic resource arising from a past event. Rimu could avoid the replacement cost by selling the building, deferring the work or repairing the roof; no contract has been signed and no one outside the company can require payment. Wearing out of the roof is an event that reduces the asset (the building), which is reflected through depreciation, not a past event creating an obligation to a third party. [1 mark]
• Even if there were an obligation, recognition requires relevant information and a faithful representation; here the amount, timing and probability are unknown (no quote), so measurement uncertainty is high and the information would not be a faithful representation. The $18 000 should be reversed: Dr Provision for roof replacement $18 000, Cr Expense $18 000. [1 mark]
Your sample is downloading. Liked it? NCEA Scholarship Accounting Paper 1 is the full paper: four questions of 8 points (32 in all) in three hours: the Conceptual Framework, company statements with ratios and a lending decision, a current issue, and a cost-volume-profit report, with a worked solution for every part showing the score band, with a worked solution for every question.
Get Paper 1 for A$11.99See all 20 papers from A$11.99More free NCEA (New Zealand) samples
Questions about this sample
What is in the NCEA Scholarship Accounting free sample?
The first 3 questions from paper 1 of the set, in the real exam layout, followed by the step-by-step worked answers. It is a 5-page PDF; this page shows the opening pages.
How many full NCEA Scholarship Accounting papers are there?
20 original papers for New Zealand Year 13 students preparing for NZ Scholarship Accounting (standard 93203). Each is four questions of 8 points (32 in all) in three hours: the Conceptual Framework, company statements with ratios and a lending decision, a current issue, and a cost-volume-profit report, with a worked solution for every part showing the score band, with a worked solution for every question. Papers start at A$11.99 and download instantly as a PDF.
Are these official past papers?
No. The sample is taken from our own original practice paper and is not an official past paper or affiliated with any exam authority.